
Riskfolio-Lib
Quantitative Strategic Asset Allocation, easy for you.
Description
Riskfolio-Lib is a library for making quantitative strategic asset allocation or portfolio optimization in Python. It is built on top of cvxpy and closely integrated with pandas data structures.
Some of key functionality that Riskfolio-Lib offers:
- Portfolio optimization with 4 objective functions (Minimum Risk, Maximum Return, Maximum Risk Adjusted Return Ratio and Maximum Utility Function)
- Portfolio optimization with 10 convex risk measures (Std. Dev., MAD, CVaR, Maximum Drawdown, among others)
- Portfolio optimization with Black Litterman model.
- Portfolio optimization with Risk Factors model.
- Portfolio optimization with constraints on tracking error and turnover.
- Portfolio optimization with short positions and leverage.
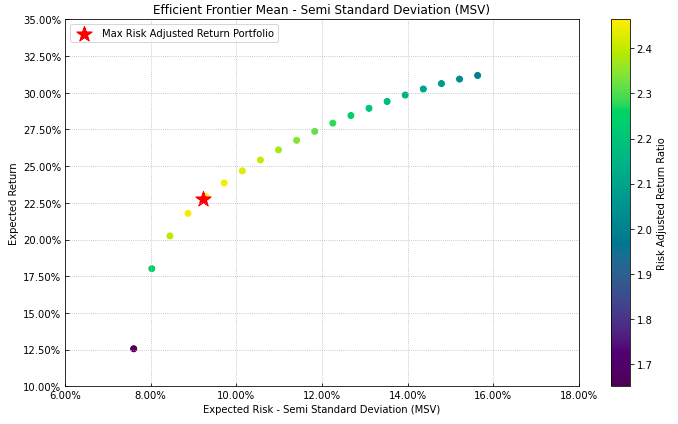
- Tools for construct efficient frontier for 10 risk measures.
- Tools for construct linear constraints on assets, asset classes and risk factors.
- Tools for construct views on assets and asset classes.
- Tools for calculate risk measures.
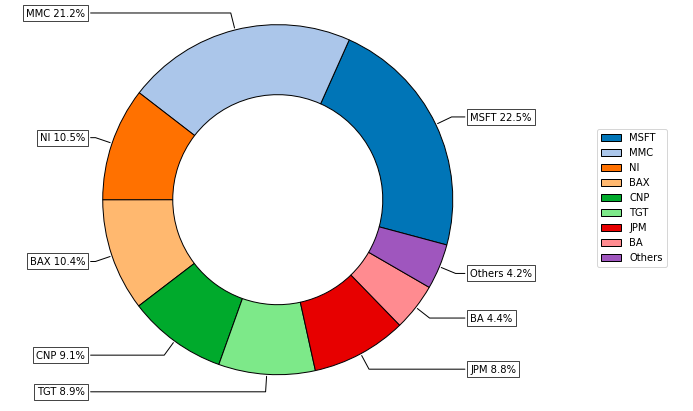
- Tools for visualizing portfolio properties and risk measures.
Documentation
Online documentation is available at Documentation.
The docs include a tutorial with examples that shows the capacities of Riskfolio-Lib.
Dependencies
Riskfolio-Lib supports Python 3.6+.
Installation requires:
- numpy >= 1.17.0
- scipy >= 1.0.1
- pandas >= 1.0.0
- matplotlib >= 3.0.0
- cvxpy >= 1.0.15
- scikit-learn >= 0.22.0
- statsmodels >= 0.10.1
Installation
The latest stable release (and older versions) can be installed from PyPI:
pip install riskfolio-lib
Development
Riskfolio-Lib development takes place on Github: https://github.com/dcajasn/Riskfolio-Lib
1 maintainer

Metadata
1 maintainer
Release files for riskfolio-lib 0.0.1
For a detailed explanation of source distributions (sdists) and built distributions (wheels), please see the package formats documentation.
Source distribution (sdist)
| File | Size | Uploaded | |
|---|---|---|---|
| Riskfolio-Lib-0.0.1.tar.gz | 11.2 MB | Details |
Built distribution (wheel)
| File | Interpreter | ABI | Platform | Reset |
|---|---|---|---|---|
| Riskfolio_Lib-0.0.1-py3-none-any.whl | Python 3 | none | any | Details |
Total release size: 11.2 MB
Release files / Riskfolio-Lib-0.0.1.tar.gz
| Download URL | Riskfolio-Lib-0.0.1.tar.gz |
|---|---|
| Size | 11.2 MB |
| Tags | Source |
|
SHA-256 checksum How to use checksums |
b61d198522858d0cf1d190c67521d58b26a74280103b5405c1ca270aa8667718
|
|
BLAKE2b-256 checksum How to use checksums |
c84d24ca558ab49ced88852dec3c10c18682024c02bad9101b52a538a024276f
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/3.1.1 pkginfo/1.5.0.1 requests/2.22.0 setuptools/42.0.2.post20191203 requests-toolbelt/0.9.1 tqdm/4.40.2 CPython/3.7.5
|
Release files / Riskfolio_Lib-0.0.1-py3-none-any.whl
| Download URL | Riskfolio_Lib-0.0.1-py3-none-any.whl |
|---|---|
| Size | 29.1 kB |
| Tags | Python 3 |
|
SHA-256 checksum How to use checksums |
03f3d44ac6c4ba7be51c7d982108f9906868ece80c57c58b2b5c250634fd875f
|
|
BLAKE2b-256 checksum How to use checksums |
cb3c183a76d9427bb898d5bf293422662a5b4e3914b55740a41c8aecc86bfa17
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/3.1.1 pkginfo/1.5.0.1 requests/2.22.0 setuptools/42.0.2.post20191203 requests-toolbelt/0.9.1 tqdm/4.40.2 CPython/3.7.5
|














