
Riskfolio-Lib
Quantitative Strategic Asset Allocation, easy for you.
Description
Riskfolio-Lib is a library for making quantitative strategic asset allocation or portfolio optimization in Python made in Peru 🇵🇪. It is built on top of cvxpy and closely integrated with pandas data structures.
Some of key functionality that Riskfolio-Lib offers:
- Portfolio optimization with 4 objective functions (Minimum Risk, Maximum Return, Maximum Risk Adjusted Return Ratio and Maximum Utility Function)
- Portfolio optimization with 10 convex risk measures (Std. Dev., MAD, CVaR, Maximum Drawdown, among others)
- Risk Parity Portfolio optimization with 7 convex risk measures (Std. Dev., MAD, CVaR, Maximum Drawdown, among others)
- Worst Case Mean Variance Portfolio optimization.
- Portfolio optimization with Black Litterman model.
- Portfolio optimization with Risk Factors model.
- Portfolio optimization with constraints on tracking error and turnover.
- Portfolio optimization with short positions and leveraged portfolios.
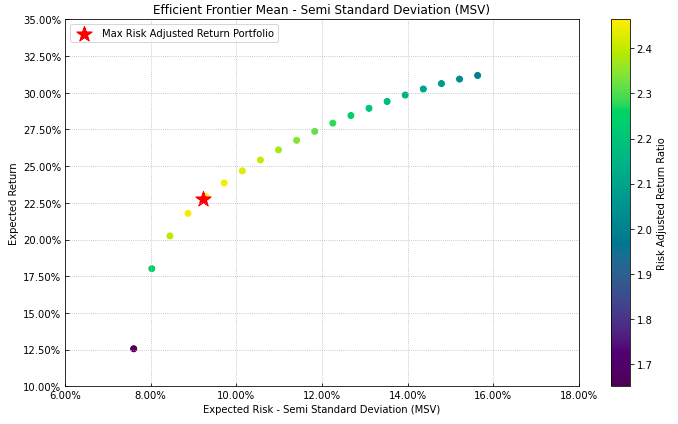
- Tools for build efficient frontier for 10 risk measures.
- Tools for build linear constraints on assets, asset classes and risk factors.
- Tools for build views on assets and asset classes.
- Tools for calculate risk measures.
- Tools for calculate risk contributions per asset.
- Tools for calculate uncertainty sets for mean vector and covariance matrix.
- Tools for estimate loadings matrix (Stepwise Regression and Principal Components Regression).
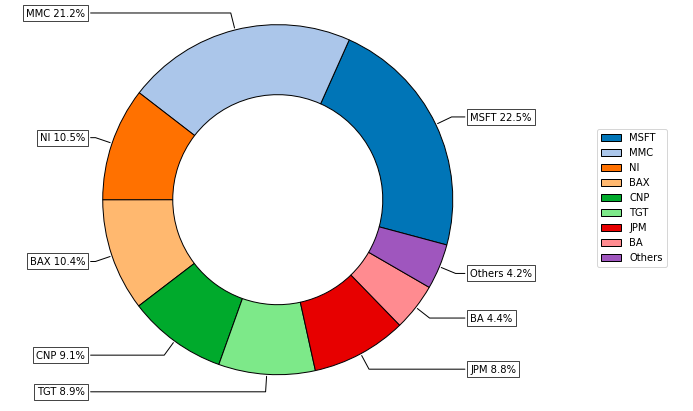
- Tools for visualizing portfolio properties and risk measures.
Documentation
Online documentation is available at Documentation.
The docs include a tutorial with examples that shows the capacities of Riskfolio-Lib.
Dependencies
Riskfolio-Lib supports Python 3.7+.
Installation requires:
- numpy >= 1.17.0
- scipy >= 1.1.0
- pandas >= 1.0.0
- matplotlib >= 3.3.0
- cvxpy >= 1.0.15
- scikit-learn >= 0.22.0
- statsmodels >= 0.10.1
- arch >= 4.15
Installation
The latest stable release (and older versions) can be installed from PyPI:
pip install riskfolio-lib
Development
Riskfolio-Lib development takes place on Github: https://github.com/dcajasn/Riskfolio-Lib
RoadMap
The plan for this module is to add more functions that will be very useful to asset managers.
- Mean Entropic Risk Optimization Portfolios.
- Add functions to estimate Duration, Convexity, Key Rate Durations and Convexities of bonds without embedded options (for loadings matrix).
- Add more functions based on suggestion of users.
1 maintainer

Metadata
1 maintainer
Release files for riskfolio-lib 0.0.6
For a detailed explanation of source distributions (sdists) and built distributions (wheels), please see the package formats documentation.
Source distribution (sdist)
| File | Size | Uploaded | |
|---|---|---|---|
| Riskfolio-Lib-0.0.6.tar.gz | 4.5 MB | Details |
Built distribution (wheel)
| File | Interpreter | ABI | Platform | Reset |
|---|---|---|---|---|
| Riskfolio_Lib-0.0.6-py3-none-any.whl | Python 3 | none | any | Details |
Total release size: 4.5 MB
Release files / Riskfolio-Lib-0.0.6.tar.gz
| Download URL | Riskfolio-Lib-0.0.6.tar.gz |
|---|---|
| Size | 4.5 MB |
| Tags | Source |
|
SHA-256 checksum How to use checksums |
f57d1717f7af30fed2c59ec0182b56e7ab215231359bb73b566f3f77d87a446c
|
|
BLAKE2b-256 checksum How to use checksums |
693ba21be66f9f95c12eb6fcfa527da998a9494ac7dab598809080e43b11fdf8
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/3.2.0 pkginfo/1.6.1 requests/2.24.0 setuptools/51.1.0.post20201221 requests-toolbelt/0.9.1 tqdm/4.50.2 CPython/3.8.5
|
Release files / Riskfolio_Lib-0.0.6-py3-none-any.whl
| Download URL | Riskfolio_Lib-0.0.6-py3-none-any.whl |
|---|---|
| Size | 36.1 kB |
| Tags | Python 3 |
|
SHA-256 checksum How to use checksums |
6463be7feca3044524c278165834dc5307f4d33016182d1b99d2686f94066220
|
|
BLAKE2b-256 checksum How to use checksums |
2bcc469d76edd78f8eaf1801b14a0a5ee9283f242e1e2b841d522e88fc7e4994
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/3.2.0 pkginfo/1.6.1 requests/2.24.0 setuptools/51.1.0.post20201221 requests-toolbelt/0.9.1 tqdm/4.50.2 CPython/3.8.5
|














