
Riskfolio-Lib
Quantitative Strategic Asset Allocation, Easy for Everyone.


Description
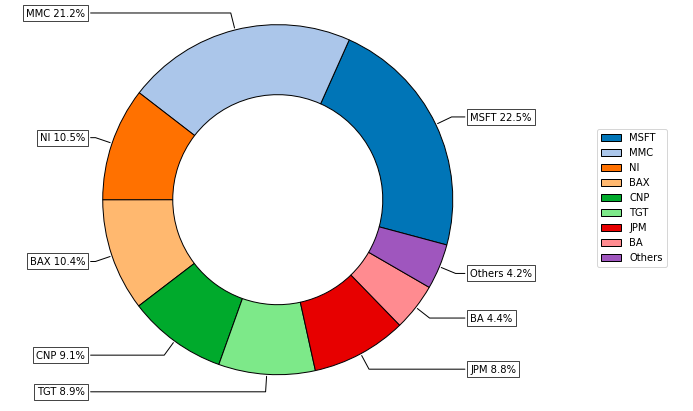
Riskfolio-Lib is a library for making quantitative strategic asset allocation or portfolio optimization in Python made in Peru 🇵🇪. Its objective is to help students, academics and practitioners to build investment portfolios based on mathematically complex models with low effort. It is built on top of cvxpy and closely integrated with pandas data structures.
Some of key functionalities that Riskfolio-Lib offers:
-
Mean Risk and Logarithmic Mean Risk (Kelly Criterion) Portfolio Optimization with 4 objective functions:
- Minimum Risk.
- Maximum Return.
- Maximum Utility Function.
- Maximum Risk Adjusted Return Ratio.
-
Mean Risk and Logarithmic Mean Risk (Kelly Criterion) Portfolio Optimization with 13 convex risk measures:
- Standard Deviation.
- Semi Standard Deviation.
- Mean Absolute Deviation (MAD).
- First Lower Partial Moment (Omega Ratio)
- Second Lower Partial Moment (Sortino Ratio)
- Conditional Value at Risk (CVaR).
- Entropic Value at Risk (EVaR).
- Worst Case Realization (Minimax Model)
- Maximum Drawdown (Calmar Ratio)
- Average Drawdown
- Conditional Drawdown at Risk (CDaR).
- Entropic Drawdown at Risk (EDaR).
- Ulcer Index.
-
Risk Parity Portfolio Optimization with 10 convex risk measures:
- Standard Deviation.
- Semi Standard Deviation.
- Mean Absolute Deviation (MAD).
- First Lower Partial Moment (Omega Ratio)
- Second Lower Partial Moment (Sortino Ratio)
- Conditional Value at Risk (CVaR).
- Entropic Value at Risk (EVaR).
- Conditional Drawdown at Risk (CDaR).
- Entropic Drawdown at Risk (EDaR).
- Ulcer Index.
-
Worst Case Mean Variance Portfolio Optimization.
-
Portfolio optimization with Black Litterman model.
-
Portfolio optimization with Risk Factors model.
-
Portfolio optimization with Black Litterman Bayesian model.
-
Portfolio optimization with Augmented Black Litterman model.
-
Portfolio optimization with constraints on tracking error and turnover.
-
Portfolio optimization with short positions and leveraged portfolios.
-
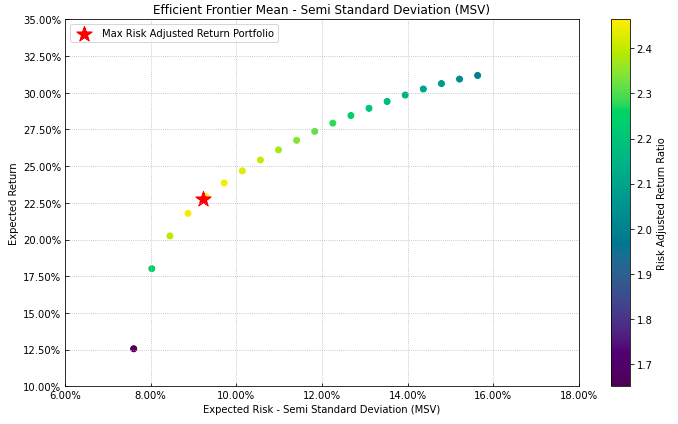
Tools to build efficient frontier for 13 risk measures.
-
Tools to build linear constraints on assets, asset classes and risk factors.
-
Tools to build views on assets and asset classes.
-
Tools to build views on risk factors.
-
Tools to calculate risk measures.
-
Tools to calculate risk contributions per asset.
-
Tools to calculate uncertainty sets for mean vector and covariance matrix.
-
Tools to estimate loadings matrix (Stepwise Regression and Principal Components Regression).
-
Tools to visualizing portfolio properties and risk measures.
-
Tools to build reports on Jupyter Notebook and Excel.
-
Option to use commercial optimization solver like MOSEK or GUROBI for large scale problems.
Documentation
Online documentation is available at Documentation.
The docs include a tutorial with examples that shows the capacities of Riskfolio-Lib.
Dependencies
Riskfolio-Lib supports Python 3.7+.
Installation requires:
- numpy >= 1.17.0
- scipy >= 1.1.0
- pandas >= 1.0.0
- matplotlib >= 3.3.0
- cvxpy >= 1.0.15
- scikit-learn >= 0.22.0
- statsmodels >= 0.10.1
- arch >= 4.15
- xlsxwriter >= 1.3.7
Installation
The latest stable release (and older versions) can be installed from PyPI:
pip install riskfolio-lib
Development
Riskfolio-Lib development takes place on Github: https://github.com/dcajasn/Riskfolio-Lib
RoadMap
The plan for this module is to add more functions that will be very useful to asset managers.
- Add Hierarchical Equal Risk Contribution portfolio and other risk parity portfolios based on vanilla risk parity model.
- Add functions to estimate Duration, Convexity, Key Rate Durations and Convexities of bonds without embedded options (for loadings matrix).
- Add more functions based on suggestion of users.
1 maintainer

Metadata
1 maintainer
Release files for riskfolio-lib 0.2.0.2
For a detailed explanation of source distributions (sdists) and built distributions (wheels), please see the package formats documentation.
Source distribution (sdist)
| File | Size | Uploaded | |
|---|---|---|---|
| Riskfolio-Lib-0.2.0.2.tar.gz | 4.2 MB | Details |
Built distribution (wheel)
| File | Interpreter | ABI | Platform | Reset |
|---|---|---|---|---|
| Riskfolio_Lib-0.2.0.2-py3-none-any.whl | Python 3 | none | any | Details |
Total release size: 4.3 MB
Release files / Riskfolio-Lib-0.2.0.2.tar.gz
| Download URL | Riskfolio-Lib-0.2.0.2.tar.gz |
|---|---|
| Size | 4.2 MB |
| Tags | Source |
|
SHA-256 checksum How to use checksums |
987cd91ad4f94b215dacb387fe119bdf46d8d6be4163cc8d3bff679b433d41f6
|
|
BLAKE2b-256 checksum How to use checksums |
38c9b60db170c2308cc055b1a86d106479343e5c44d3b6673f9d8b982dca3183
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/3.3.0 pkginfo/1.7.0 requests/2.25.1 setuptools/52.0.0.post20210125 requests-toolbelt/0.9.1 tqdm/4.59.0 CPython/3.8.5
|
Release files / Riskfolio_Lib-0.2.0.2-py3-none-any.whl
| Download URL | Riskfolio_Lib-0.2.0.2-py3-none-any.whl |
|---|---|
| Size | 48.1 kB |
| Tags | Python 3 |
|
SHA-256 checksum How to use checksums |
f3d4c40544bad0d09c026d2fca758af93ec2cd33d29dffb6f30866cba7bf26a1
|
|
BLAKE2b-256 checksum How to use checksums |
b843c41363bf8a899fcf95b6145b239113d9297af8dd720da8fdb86dbac1b113
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/3.3.0 pkginfo/1.7.0 requests/2.25.1 setuptools/52.0.0.post20210125 requests-toolbelt/0.9.1 tqdm/4.59.0 CPython/3.8.5
|














