
jquants-algo


jquants-algo is a python library for algorithmic trading with japanese stock trade using J-Quants on Python 3.8 and above.
Installation
$ pip install jquants-algo
Usage
backtest
from jquants_algo import Algo
import pprint

class MyAlgo(Algo):
    def strategy(self):
        fast_ma = self.sma(period=3)
        slow_ma = self.sma(period=5)
        # golden cross
        self.sell_exit = self.buy_entry = (fast_ma > slow_ma) & (
            fast_ma.shift() <= slow_ma.shift()
        )
        # dead cross
        self.buy_exit = self.sell_entry = (fast_ma < slow_ma) & (
            fast_ma.shift() >= slow_ma.shift()
        )

algo = MyAlgo(
    mail_address="<your J-Quants mail address>",
    password="<your J-Quants password>",
    ticker="7203",  # TOYOTA
    size=100,  # 100 shares
)
pprint.pprint(algo.backtest())
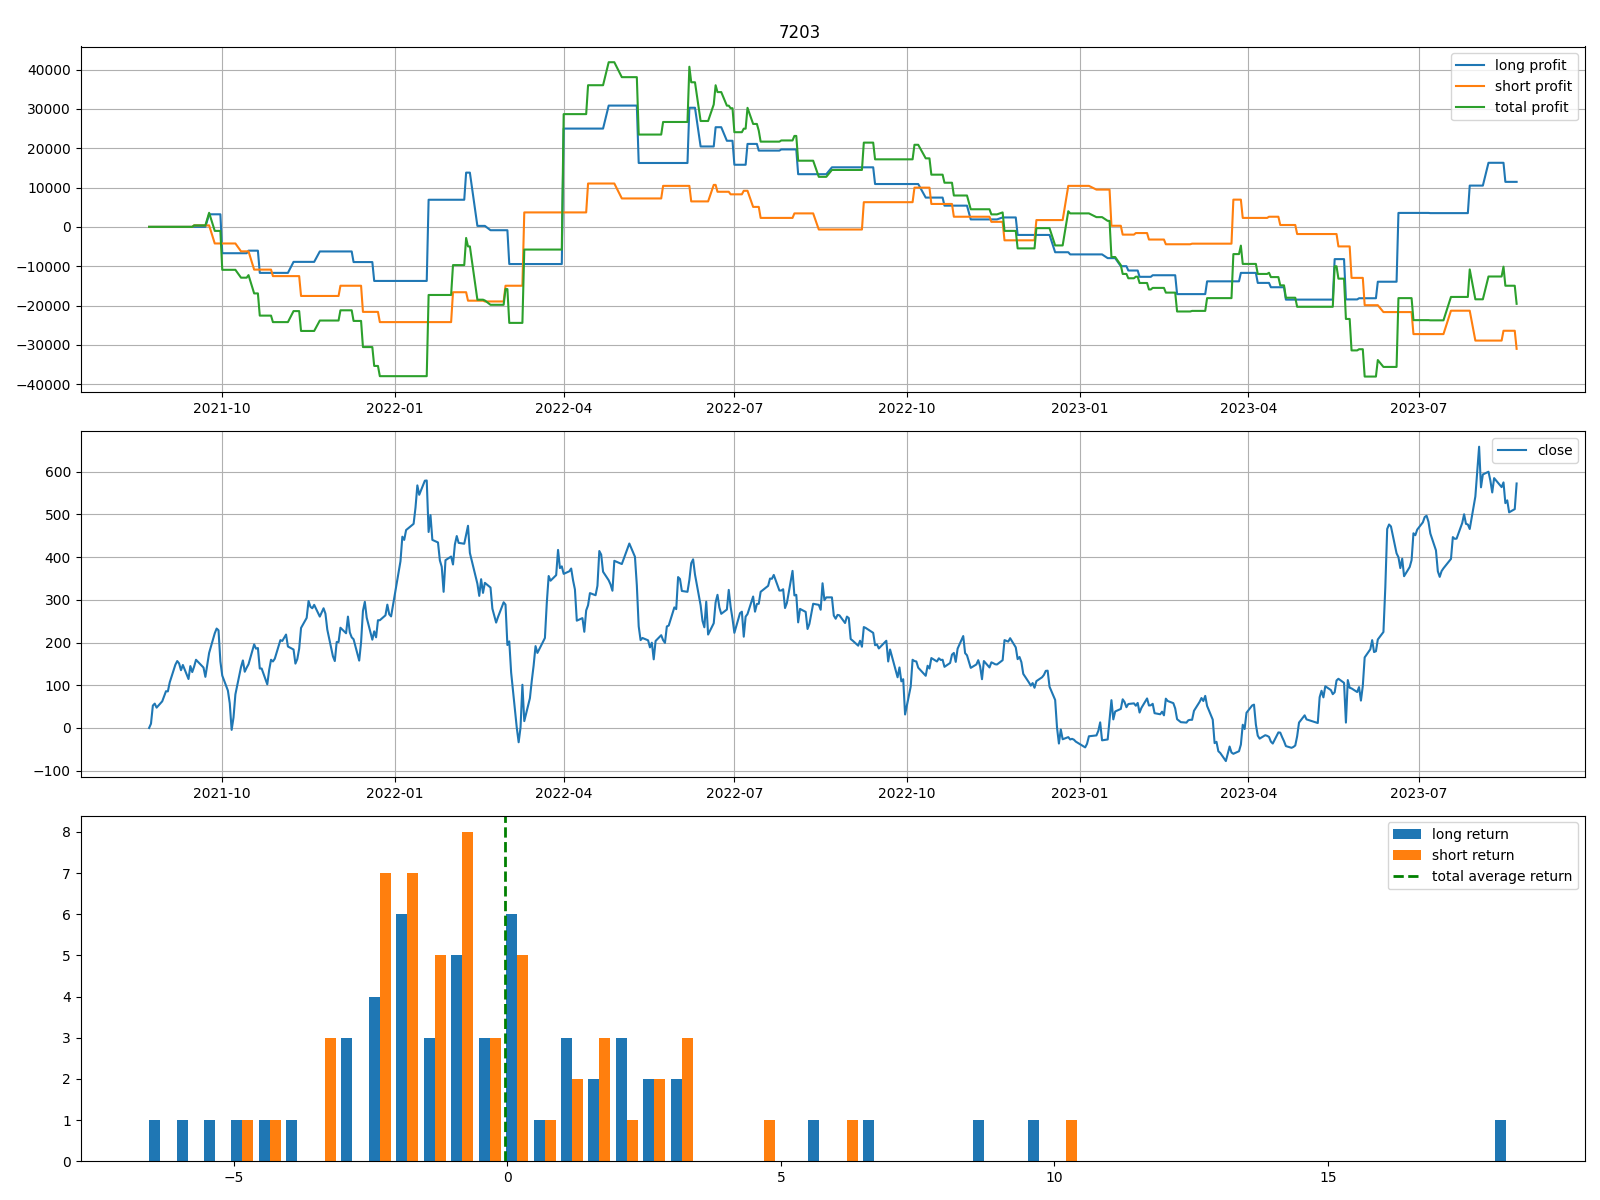
{'long': {'average return': '0.156',
          'maximum drawdown': '49350.000',
          'profit': '11450.000',
          'profit factor': '1.080',
          'riskreward ratio': '1.455',
          'sharpe ratio': '0.038',
          'trades': '54.000',
          'win rate': '0.426'},
 'short': {'average return': '-0.238',
           'maximum drawdown': '42050.000',
           'profit': '-31020.000',
           'profit factor': '0.754',
           'riskreward ratio': '1.319',
           'sharpe ratio': '-0.091',
           'trades': '55.000',
           'win rate': '0.364'},
 'total': {'average return': '-0.043',
           'maximum drawdown': '79950.000',
           'profit': '-19570.000',
           'profit factor': '0.927',
           'riskreward ratio': '1.423',
           'sharpe ratio': '-0.013',
           'trades': '109.000',
           'win rate': '0.394'}}
predict
from jquants_algo import Algo
import pprint

class MyAlgo(Algo):
    def strategy(self):
        fast_ma = self.sma(period=3)
        slow_ma = self.sma(period=5)
        # golden cross
        self.sell_exit = self.buy_entry = (fast_ma > slow_ma) & (
            fast_ma.shift() <= slow_ma.shift()
        )
        # dead cross
        self.buy_exit = self.sell_entry = (fast_ma < slow_ma) & (
            fast_ma.shift() >= slow_ma.shift()
        )

algo = MyAlgo(
    mail_address="<your J-Quants mail address>",
    password="<your J-Quants password>",
    ticker="7203",  # TOYOTA
    size=100,  # 100 shares
)
pprint.pprint(algo.predict())
{'buy entry': True,
 'buy exit': False,
 'close': 2416.5,
 'date': '2023-08-22',
 'sell entry': False,
 'sell exit': True}
advanced
from jquants_algo import Algo
import pprint

class MyAlgo(Algo):
    def strategy(self):
        rsi = self.rsi(period=10)
        ema = self.ema(period=20)
        lower = ema - (ema * 0.001)
        upper = ema + (ema * 0.001)
        self.buy_entry = (rsi < 30) & (self.df.Close < lower)
        self.sell_entry = (rsi > 70) & (self.df.Close > upper)
        self.sell_exit = ema > self.df.Close
        self.buy_exit = ema < self.df.Close

algo = MyAlgo(
    mail_address="<your J-Quants mail address>",
    password="<your J-Quants password>",
    ticker="7203",  # TOYOTA
    size=100,  # 100 shares
    outputs_dir_path="outputs",
    data_dir_path="data",
)
pprint.pprint(algo.backtest())
pprint.pprint(algo.predict())
Supported indicators
- Simple Moving Average 'sma'
- Exponential Moving Average 'ema'
- Moving Average Convergence Divergence 'macd'
- Relative Strenght Index 'rsi'
- Bollinger Bands 'bbands'
- Market Momentum 'mom'
- Stochastic Oscillator 'stoch'
- Average True Range 'atr'
Getting started
For help getting started with J-Quants, view our online documentation.
1 maintainer

Metadata
1 maintainer
Release files for jquants-algo 0.1.1
For a detailed explanation of source distributions (sdists) and built distributions (wheels), please see the package formats documentation.
Source distribution (sdist)
| File | Size | Uploaded | |
|---|---|---|---|
| jquants-algo-0.1.1.tar.gz | 7.3 kB | Details |
Built distribution (wheel)
| File | Interpreter | ABI | Platform | Reset |
|---|---|---|---|---|
| jquants_algo-0.1.1-py3-none-any.whl | Python 3 | none | any | Details |
Total release size: 14.1 kB
Release files / jquants-algo-0.1.1.tar.gz
| Download URL | jquants-algo-0.1.1.tar.gz |
|---|---|
| Size | 7.3 kB |
| Tags | Source |
|
SHA-256 checksum How to use checksums |
d29a6ac0af0c9ec2b53a44c4059f60772575c488fbf7763f5a67bf66f47aa376
|
|
BLAKE2b-256 checksum How to use checksums |
8a60c09d5145ed65765b529ca3d6bcf60941cc73e0cad05ba09fd02aa4c347f4
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/4.0.2 CPython/3.8.16
|
Release files / jquants_algo-0.1.1-py3-none-any.whl
| Download URL | jquants_algo-0.1.1-py3-none-any.whl |
|---|---|
| Size | 6.8 kB |
| Tags | Python 3 |
|
SHA-256 checksum How to use checksums |
7d0898dbc2f785454ef4c2c920a96ead2f0b9a6678bb7c1a0a001101395e7ef8
|
|
BLAKE2b-256 checksum How to use checksums |
8572fd25c87e1500b3abf14221c14f987289b28e9372b596e0b65d318a991a16
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/4.0.2 CPython/3.8.16
|














