


Open Margin
Arrow Markets open source repository to compute margin requirements for risky asset portfolios, including crypto options portfolios.
Overview
This repository uses VAR/CVAR methodology to compute the necessary margin required for a portfolio of BTC or ETH options. Negative values refer to the cash margin needed for a given portfolio, while positive margin values count as credits. For further details, please refer to the white paper "Automated Margin Systems in Practice".
Installation
pip install openmargin
Usage
Open Margin calculates the risk of an options portfolio through RiskCalc. A compatible ticker and an options portfolio are the minimum inputs needed to generate the corresponding margin values. Providing the options data as a dataframe to Open Margin substantially reduces margin computation time.
import datetime
import pandas as pd

ticker = "eth"

expiration = datetime.datetime.strptime('2024-09-27 08:00:00', "%Y-%m-%d %H:%M:%S")
strike = 7000.0
kind = "C"
position = -1
portfolio = {'expiration': expiration, 'strike': strike, 'kind': kind, 'position': position}
portfolio = pd.DataFrame([portfolio],columns = ["expiration", "strike", "kind", "position"])
Once the ticker and the portfolio data are ready, margin can be computed with default parameters:
from openmargin.risk import RiskCalc
risk_calculator = RiskCalc(ticker, portfolio)
risk_calculator.get_margin()
RiskCalc has four pillars that can be modified to generate the required margin. All of the examples below assume that minimum inputs and corresponding package imports are complete.
Options Data
Open Margin uses the current options data for BTC and ETH from Deribit. To provide a different dataset, please provide a pandas dataframe containing options data similar to the one shown below:
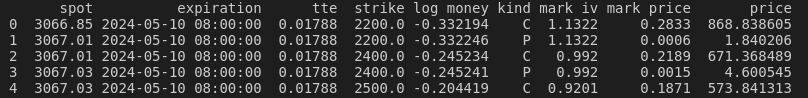
To download and save the most recent options data:
from openmargin.auxiliary import deribit_option_data

utcnow = datetime.datetime.now(tz=datetime.timezone.utc)
(expiration_datetimes, yearly_times_to_expiration, strikes, log_moneynesses, contract_types, spot_prices, yearly_mark_implied_volatilities, mark_prices, prices) = deribit_option_data(ticker, utcnow)
options_data = pd.DataFrame([spot_prices, expiration_datetimes, yearly_times_to_expiration, strikes, log_moneynesses, contract_types, yearly_mark_implied_volatilities, mark_prices, prices]).T
options_data.columns = ['spot', 'expiration','tte','strike', 'log_money', 'kind','mark_iv','mark_price', 'price']
options_data = options_data.reset_index(drop=True)
options_data.to_csv(f'options_data.csv', index = False)
To load a cahced option dataset and get the corresponding margin values:
options_data = pd.read_csv('options_data.csv', parse_dates=['expiration'])
risk_calculator = RiskCalc(ticker, portfolio, options_data)
risk_calculator.get_margin()
Risk Configuration
Three main risk factors are configured under RiskConfig. Interest rate, sampling frequency and steps are the key parameters currently allowed for user customization. Sampling frequency multiplied by steps determine the trading horizon that will be used to calculate margin values.
from openmargin.risk import RiskConfig, RiskCalc

r = 0.02
sampling_frequency = 4 # hours
steps = 6
risk_params = RiskConfig(r, sampling_frequency, steps)

risk_calculator = RiskCalc(ticker, portfolio, risk_params = risk_params)
risk_calculator.get_margin()
Risk Model
RiskModel class determines the margin method used. Open Margin only allows VAR type margin methods in this public version. To select between VAR and CVAR and to change margin threshold:
from openmargin.risk import VAR, RiskModel, RiskCalc

var_type = 'VAR'
var_threshold = 0.05
margin_method = VAR(var_type, var_threshold)
risk_model = RiskModel(margin_method)

risk_calculator = RiskCalc(ticker, portfolio, risk_model = risk_model)
risk_calculator.get_margin()
Price Paths
Path dependant methods like VAR/CVAR depend on future price paths. 1,000 paths are generated by default by PricePathGenerator. Changes to the default number of paths can be made via:
from openmargin.auxiliary import get_underlier_price
from openmargin.risk import PricePathGenerator, RiskCalc

spot = get_underlier_price(ticker)
number_of_paths = 10_000
price_paths = PricePathGenerator(ticker, risk_params, spot, number_of_paths)

risk_calculator = RiskCalc(ticker, portfolio, price_paths = price_paths)
risk_calculator.get_margin()
The paths can be generated with:
sample_paths = price_paths.generate_paths()
Further customization examples can be found under example.py.
Clone Repo Directly
The repo can also be cloned directly. This is advisable for doing work on the openmargin repo itself. Please see our guidelines for submitting pull requests. Community contributions are welcome!
git clone https://github.com/Arrow-Markets-Research/openmargin
cd openmargin
venv
Initialize a virtual environment (Windows)
python3 -m venv venv
venv/Scripts/activate.bat
Dependencies
From the venv, run
pip install -r requirements.txt
Create a test file in the src/openmargin directory called om-test.py:
import datetime
import pandas as pd
from openmargin.risk import RiskCalc

ticker = "eth"

expiration = datetime.datetime.strptime('2024-09-27 08:00:00', "%Y-%m-%d %H:%M:%S")
strike = 7000.0
kind = "C"
position = -1
portfolio = {'expiration': expiration, 'strike': strike, 'kind': kind, 'position': position}
portfolio = pd.DataFrame([portfolio],columns = ["expiration", "strike", "kind", "position"])

risk_calculator = RiskCalc(ticker, portfolio)
m = risk_calculator.get_margin()

print("portfolio:\n", portfolio, "\nspot:", float(risk_calculator.portfolio.spot), "\ninitial margin:", m[0])
Now, to compute the intitial margin for the chosen portfolio, switch to the src directory and run
python3 -m openmargin.om-test
1 maintainer

Metadata
1 maintainer
Release files for openmargin 0.0.7
For a detailed explanation of source distributions (sdists) and built distributions (wheels), please see the package formats documentation.
Source distribution (sdist)
| File | Size | Uploaded | |
|---|---|---|---|
| openmargin-0.0.7.tar.gz | 74.9 kB | Details |
Built distribution (wheel)
| File | Interpreter | ABI | Platform | Reset |
|---|---|---|---|---|
| openmargin-0.0.7-py3-none-any.whl | Python 3 | none | any | Details |
Total release size: 111.2 kB
Release files / openmargin-0.0.7.tar.gz
| Download URL | openmargin-0.0.7.tar.gz |
|---|---|
| Size | 74.9 kB |
| Tags | Source |
|
SHA-256 checksum How to use checksums |
1d43bcc9f2dfc6786e26690f56f2222890642f9cada5aedac0836a04889a8de4
|
|
BLAKE2b-256 checksum How to use checksums |
28855d49e8aa76098825757c116797ce53aef93fcae1d7b423d7c410a1e85ff8
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/5.1.0 CPython/3.8.10
|
Release files / openmargin-0.0.7-py3-none-any.whl
| Download URL | openmargin-0.0.7-py3-none-any.whl |
|---|---|
| Size | 36.3 kB |
| Tags | Python 3 |
|
SHA-256 checksum How to use checksums |
fcf0555d5e3f40446cac8b1448f347589c53359f12cd62ca043c9229be03ab66
|
|
BLAKE2b-256 checksum How to use checksums |
46707ad268cf70d8886c6bda8f916278b2af50b90d52a05aeef1ef767d157c22
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/5.1.0 CPython/3.8.10
|













