
Option Risk Explain
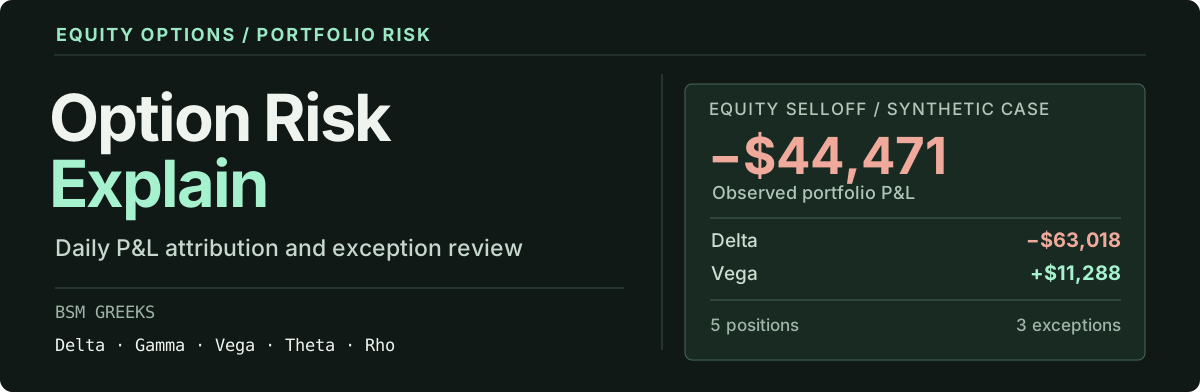
Explain an equity-option portfolio's daily P&L from opening Greeks, model revaluation and changes in market marks. Inspect the factor contributions, reconcile the difference and identify contracts that need review.
Python 3.10+ · Python API / CLI / browser · Local CSV analysis · No Streamlit dependency
See the desk move
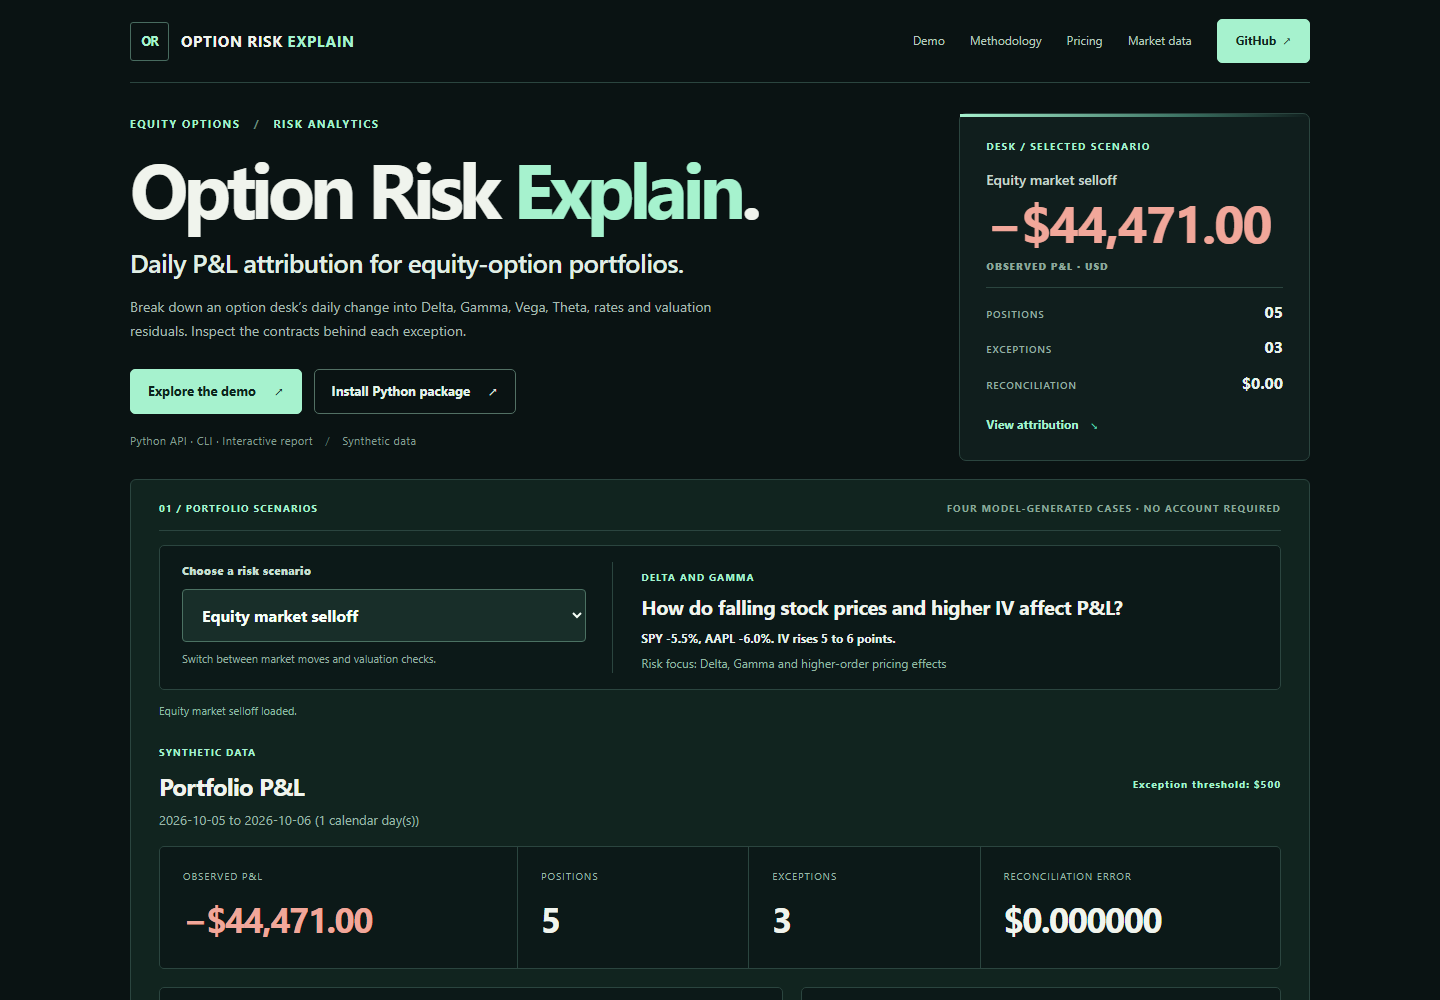
The interactive report opens with a five-position SPY/AAPL book. Choose Equity market selloff to inspect a shock where SPY falls 5.5%, AAPL falls 6.0% and implied volatility rises by 5–6 percentage points.
EQUITY MARKET SELLOFF                       05–06 OCT 2026
─────────────────────────────────────────────────────────
Observed portfolio P&L                           -$44,471
  Delta                                          -$63,018
  Vega                                           +$11,288
Positions                                              5
Exceptions                                             3
P&L reconciliation error                           $0.00
All inputs are synthetic. The attribution is calculated with the same option_lab engine used for custom portfolios. Greeks, full model repricing, market/model basis and individual contract flags are available in the report.
Example portfolio
| Scenario | Observed P&L | Exceptions |
|---|---|---|
| Daily desk review | −$1,152 | 2 |
| Equity market selloff | −$44,471 | 3 |
| Volatility repricing | +$13,735 | 0 |
| Valuation exception | +$1,146 | 3 |
Switching the browser dropdown updates the report from a precomputed scenario record. No account, file upload or backend is required for these four examples.
Open the interactive GitHub Pages demo ↗
Local setup
Install from the source repository:
git clone https://github.com/garroshub/OptionRiskExplain.git
cd OptionRiskExplain
python -m pip install -e .
python -m option_lab serve
Open http://127.0.0.1:8765/. The local server also accepts two CSV snapshots under Custom portfolio analysis, with JSON and CSV export.
The Python API can run without a browser:
from pathlib import Path
from option_lab import explain_csv

report = explain_csv(
    Path("examples/positions_2026-10-05.csv").read_text(),
    Path("examples/positions_2026-10-06.csv").read_text(),
    exception_threshold=500,
)

print(report["totals"]["observed_pnl"])
print(report["totals"]["reconciliation_error"])
print(report["exceptions"])
CLI example with file exports:
python -m option_lab explain --start examples/positions_2026-10-05.csv --end examples/positions_2026-10-06.csv --threshold 500 --output report.json --csv-output contract-pnl.csv
The optional Yahoo Finance adapter is installed with pip install -e ".[market]". Market data is available through option-risk-explain quote SPY, option-risk-explain expirations SPY and the local option-chain browser. Yahoo quotes are not used as a historical institutional mark feed.
P&L calculation
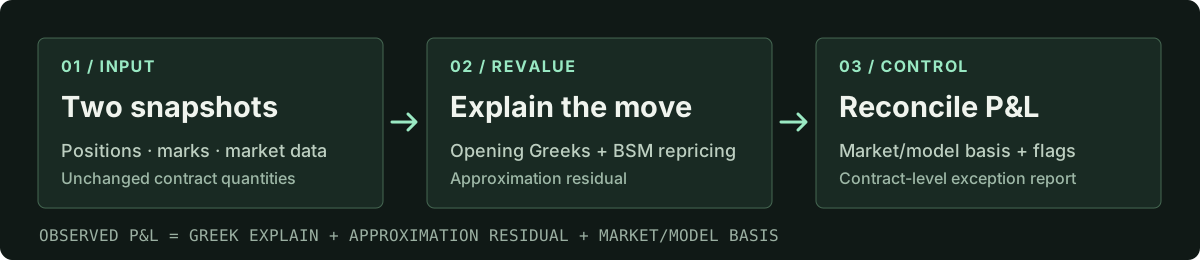
For an unchanged position, with signed contract quantity Q, multiplier M and end-of-day mark P:
Observed P&L = Q × M × (P_end − P_start)

Greek explain:
  Delta0 × ΔSpot + 0.5 × Gamma0 × ΔSpot²
  + Vega0 × ΔIV + Theta0 × elapsed_days
  + Rho0 × ΔRate + isolated dividend-yield effect
  (all multiplied by Q × M)

Approximation residual = Full BSM repricing − Greek explain
Market/model basis     = Observed P&L − Full BSM repricing

Observed P&L = Greek explain + Approximation residual + Market/model basis
Vega and Rho use percentage-point changes; Theta uses calendar days. The two residuals are displayed separately. A market/model basis change can reflect differences in model assumptions, valuation marks or timestamps.
Exception checks cover approximation/basis amounts above a user-supplied USD threshold, crossed bid/ask quotes and marks outside the provided spread.
Working with your own positions
Custom reports require two snapshots with identical contract identities, signed quantities and multipliers. Required CSV fields:
| Data | CSV fields |
|---|---|
| Contract | underlying, option_type, expiry, strike |
| Position | quantity, multiplier |
| Market inputs | as_of, spot, mark, volatility, rate, dividend_yield |
| Optional controls | bid, ask, source |
Dates use YYYY-MM-DD. Volatility, rates and dividend yields are annual decimal values (e.g. 0.25 for 25%). The opening and closing CSVs are included.
Generate the four browser cases with:
python -m scripts.make_risk_fixtures
python -m scripts.generate_scenarios
Model scope and tests
The engine uses European Black–Scholes–Merton pricing, continuous dividends and ACT/365 maturity. It assumes unchanged USD-denominated positions. Trades, fees, funding, early exercise, settlement, FX and corporate actions are excluded. It is a research and workflow prototype, not a validated bank risk system or regulatory FRTB P&L Attribution Test.
python -m unittest discover -s tests -p "test_*.py" -v
node --test tests/pricing.test.mjs
python -m build --wheel --no-isolation
python tests/wheel_smoke.py
The tests cover prices and Greeks, signed-position P&L reconciliation, input validation, scenario consistency, HTTP endpoints, and Chrome desktop/mobile interactions. The installable distribution is option-risk-explain. The Python module remains option_lab, and the original option-lab CLI remains available.
1 maintainer

Metadata
1 maintainer
Release files for option-risk-explain 0.2.0
For a detailed explanation of source distributions (sdists) and built distributions (wheels), please see the package formats documentation.
Source distribution (sdist)
| File | Size | Uploaded | |
|---|---|---|---|
| option_risk_explain-0.2.0.tar.gz | 53.3 kB | Details |
Built distribution (wheel)
| File | Interpreter | ABI | Platform | Reset |
|---|---|---|---|---|
| option_risk_explain-0.2.0-py3-none-any.whl | Python 3 | none | any | Details |
Total release size: 106.1 kB
Release files / option_risk_explain-0.2.0.tar.gz
| Download URL | option_risk_explain-0.2.0.tar.gz |
|---|---|
| Size | 53.3 kB |
| Tags | Source |
|
SHA-256 checksum How to use checksums |
265458fc204f274458ab550b8c29149ef7668d7f44c09866bcf0ff17c48e2c45
|
|
BLAKE2b-256 checksum How to use checksums |
bb81982012d6c21472359fad7c7722c25f25ccba57d48f41162b8d33eb04f098
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
Yes |
| Uploaded via |
twine/7.0.0 CPython/3.13.14
|
Provenance
Provenance describes where a file came from. On PyPI, provenance is shared via attestations, which provide a verifiable record of the build or publishing details. View details, limitations and caveats.


PyPI Publish Attestation
PyPI verified that this artifact, at this checksum, originated from the publisher listed below.
Signed by GitHub Actions, verified by PyPI on Oct 8, 2026.
Transparency logRelease files / option_risk_explain-0.2.0-py3-none-any.whl
| Download URL | option_risk_explain-0.2.0-py3-none-any.whl |
|---|---|
| Size | 52.8 kB |
| Tags | Python 3 |
|
SHA-256 checksum How to use checksums |
60d6f69ac8d2f352757f436cb41377c4f7fdd1d711625640fd7e815e59c416a2
|
|
BLAKE2b-256 checksum How to use checksums |
0d96d23d53c774a6248268e1e95907887542fed3f420210c448fb92ff85c4bab
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
Yes |
| Uploaded via |
twine/7.0.0 CPython/3.13.14
|
Provenance
Provenance describes where a file came from. On PyPI, provenance is shared via attestations, which provide a verifiable record of the build or publishing details. View details, limitations and caveats.
PyPI Publish Attestation
PyPI verified that this artifact, at this checksum, originated from the publisher listed below.
Signed by GitHub Actions, verified by PyPI on Oct 8, 2026.
Transparency log












