


Common financial return and risk metrics in Python.
Maintenance and new projects
We continue to maintain Empyrical Reloaded for bug, security, and compatibility fixes. Our new feature development focuses on ML4T Diagnostic, part of the ML4T libraries. For new projects, evaluate it through the Diagnostic documentation and Empyrical migration guide, which includes a runnable metric comparison and explains differences in defaults and results. The source migration recipe and capability reference identify tested versions, adapters and remaining gaps.
Installation
Empyrical Reloaded supports Python 3.11 through 3.15. Python 3.9 and 3.10 are retired
for this release; historical packages retain their original Python requirements.
You can install it using pip:
pip install empyrical-reloaded
or conda from the conda-forge channel
conda install empyrical-reloaded -c conda-forge
The installer provides NumPy, pandas, SciPy and the other declared runtime dependencies.
Note that Numpy>=2.0 requires pandas>=2.2.2. If you are using an older version of pandas, you may need to upgrade accordingly, otherwise you may encounter compatibility issues.
Optional dependencies include yfinance to download price data from Yahoo! Finance and pandas-datareader to access Fama-French risk factors and FRED treasury yields.
To install the optional dependencies, use:
pip install empyrical-reloaded[yfinance]
or
pip install empyrical-reloaded[datareader]
or
pip install empyrical-reloaded[yfinance,datareader]
Usage
Simple Statistics
Empyrical computes basic metrics from returns and volatility to alpha and beta, Value at Risk, and Sharpe or Sortino ratios.
import numpy as np
from empyrical import max_drawdown, alpha_beta

returns = np.array([.01, .02, .03, -.4, -.06, -.02])
benchmark_returns = np.array([.02, .02, .03, -.35, -.05, -.01])

# calculate the max drawdown
max_drawdown(returns)

# calculate alpha and beta
alpha, beta = alpha_beta(returns, benchmark_returns)
Rolling Measures
Empyrical also aggregates return and risk metrics for rolling windows:
import numpy as np
from empyrical import roll_max_drawdown

returns = np.array([.01, .02, .03, -.4, -.06, -.02])

# calculate the rolling max drawdown
roll_max_drawdown(returns, window=3)
Pandas Support
Empyrical also works with both NumPy arrays and Pandas data structures:
import pandas as pd
from empyrical import roll_up_capture, capture

returns = pd.Series([.01, .02, .03, -.4, -.06, -.02])
factor_returns = pd.Series([.02, .01, .03, -.01, -.02, .02])

# calculate a capture ratio
capture(returns, factor_returns)
-0.147387712263491
Fama-French Risk Factors
Empyrical downloads Fama-French risk factors from 1970 onward:
Requires optional dependency pandas-datareader - see installation instructions above.
import pandas as pd
import empyrical as emp

risk_factors = emp.utils.get_fama_french()

pd.concat([risk_factors.head(), risk_factors.tail()])

Mkt - RF
SMB
HML
RF
Mom
Date
1970 - 01 - 02
00: 00:00 + 00: 00
0.0118
0.0129
0.0101
0.00029 - 0.0340
1970 - 01 - 05
00: 00:00 + 00: 00
0.0059
0.0067
0.0072
0.00029 - 0.0153
1970 - 01 - 06
00: 00:00 + 00: 00 - 0.0074
0.0010
0.0021
0.00029
0.0038
1970 - 01 - 07
00: 00:00 + 00: 00 - 0.0015
0.0040 - 0.0033
0.00029
0.0011
1970 - 01 - 0
8
00: 00:00 + 00: 00
0.0004
0.0018 - 0.0017
0.00029
0.0033
2024 - 03 - 22
00: 00:00 + 00: 00 - 0.0023 - 0.0087 - 0.0053
0.00021
0.0043
2024 - 03 - 25
00: 00:00 + 00: 00 - 0.0026 - 0.0024
0.0088
0.00021 - 0.0034
2024 - 03 - 26
00: 00:00 + 00: 00 - 0.0026
0.0009 - 0.0013
0.00021
0.0009
2024 - 03 - 27
00: 00:00 + 00: 00
0.0088
0.0104
0.0091
0.00021 - 0.0134
2024 - 03 - 28
00: 00:00 + 00: 00
0.0010
0.0029
0.0048
0.00021 - 0.0044
Asset Prices and Benchmark Returns
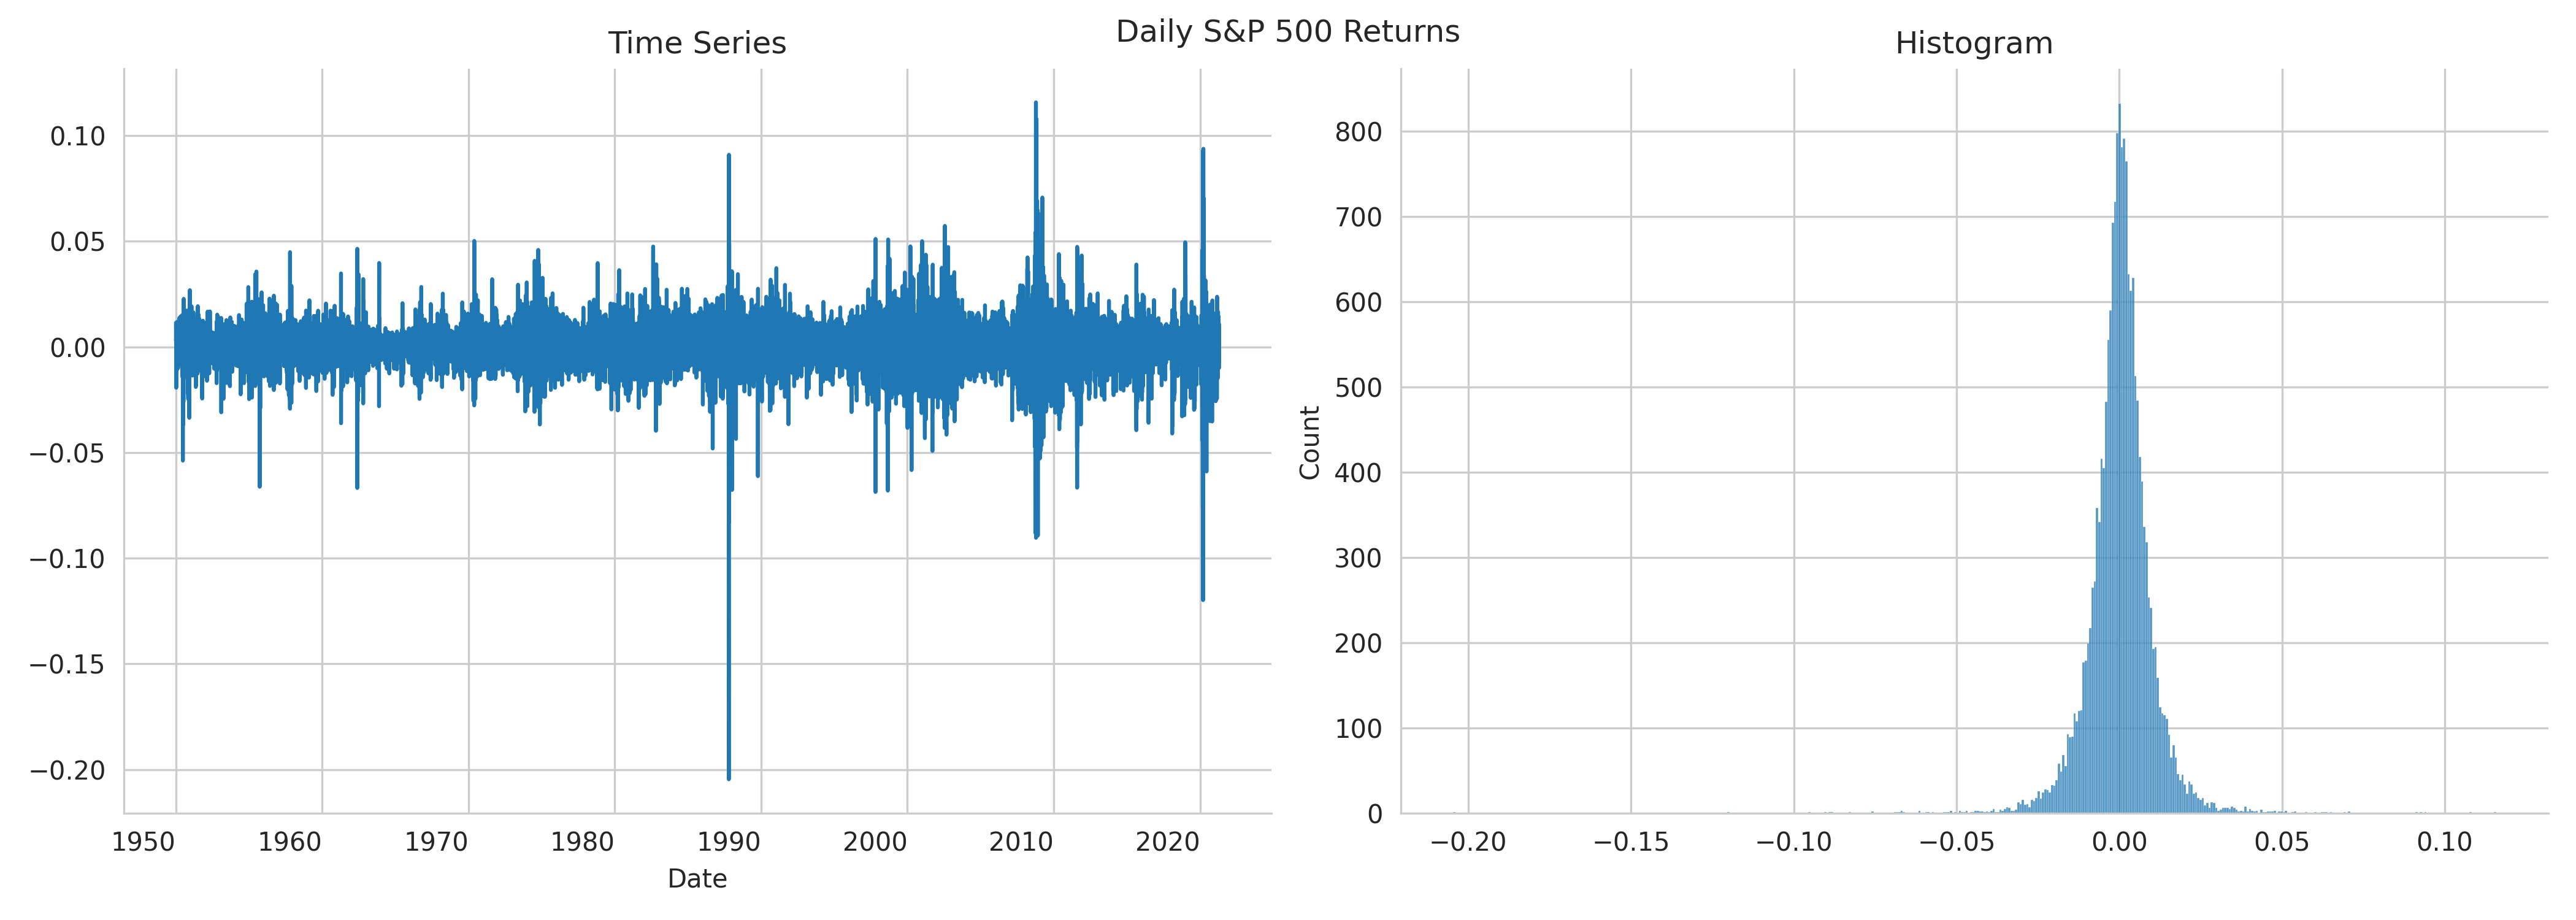
Empyrical use yfinance to download price data from Yahoo! Finance. To obtain the S&P returns since 1950, use:
Note: requires optional dependency
yfinance- see installation instructions above.
import empyrical as emp

symbol = '^GSPC'
returns = emp.utils.get_symbol_returns_from_yahoo(symbol,
                                                  start='1950-01-01')

import seaborn as sns  # requires separate installation
import matplotlib.pyplot as plt  # requires separate installation

fig, axes = plt.subplots(ncols=2, figsize=(14, 5))

with sns.axes_style('whitegrid'):
    returns.plot(ax=axes[0], rot=0, title='Time Series', legend=False)
    sns.histplot(returns, ax=axes[1], legend=False)
axes[1].set_title('Histogram')
sns.despine()
plt.tight_layout()
plt.suptitle('Daily S&P 500 Returns')
Documentation
See the documentation for details on the API.
Support
Please open an issue for support.
Contributing
Empyrical Reloaded accepts bug, security, and compatibility fixes. Read the contribution guide for issue scope, regression evidence, review checks, and AI disclosure requirements.
Testing
- install requirements
- "pytest>=6.2.0",
pytest tests
1 maintainer

Metadata
1 maintainer
Release files for empyrical-reloaded 0.7.0
For a detailed explanation of source distributions (sdists) and built distributions (wheels), please see the package formats documentation.
Source distribution (sdist)
| File | Size | Uploaded | Provenance | Actions |
|---|---|---|---|---|
| empyrical_reloaded-0.7.0.tar.gz | 148.8 kB | Without provenance | Details for empyrical_reloaded-0.7.0.tar.gz |
Built distribution (wheel)
| File | Interpreter | ABI | Platform | Actions Reset |
|---|---|---|---|---|
| empyrical_reloaded-0.7.0-py3-none-any.whl | Python 3 | none | any | Details for empyrical_reloaded-0.7.0-py3-none-any.whl |
Total release size: 179.6 kB
Release files / empyrical_reloaded-0.7.0.tar.gz
| Download URL | empyrical_reloaded-0.7.0.tar.gz |
|---|---|
| Size | 148.8 kB |
| Tags | Source |
|
SHA-256 checksum How to use checksums |
6c5dce2c9bdfb2f171c20da04d1b94ca4218a5ffc411909c64ec37de34b6874d
|
|
BLAKE2b-256 checksum How to use checksums |
68d7e03fe9341c28d966c7b03b575dc38a6054ebb52e2aa5a3c75dc5892ff24a
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/7.0.0 CPython/3.13.14
|
Release files / empyrical_reloaded-0.7.0-py3-none-any.whl
| Download URL | empyrical_reloaded-0.7.0-py3-none-any.whl |
|---|---|
| Size | 30.8 kB |
| Tags | Python 3 |
|
SHA-256 checksum How to use checksums |
7ba3b720f188db3f0f4e9a3e3d67c0864481478200c321439154f8844b70b1af
|
|
BLAKE2b-256 checksum How to use checksums |
8fcb9dc3c4b1b8ddaafae93fc1cf0bfb26469c2156f0e06c2ed4ae24fc9de6c2
|
| Upload date | |
|
Uploaded using Trusted Publishing? What is trusted publishing? |
No |
| Uploaded via |
twine/7.0.0 CPython/3.13.14
|
Security for empyrical-reloaded 0.7.0
Provenance
Provenance describes where a file came from. On PyPI, provenance is shared via attestations, which provide a verifiable record of the build or publishing details. View details, limitations and caveats.
No provenance found
None of the files in this release were uploaded with provenance metadata.
A note on package security
PyPI is a repository for distributing packages, not a service for auditing them. While third-party security researchers and our staff do their best to detect and remove malicious packages, PyPI cannot guarantee the quality, security or suitability of any given package.
To learn more about protecting yourself from malicious actors, visit our package security documentation.














